SECURE 2.0

Turn complexity into opportunity with SECURE 2.0. Pinpoint the provisions that help you win business, strengthen client value, and lead more confident conversations.

SECURE 2.0 Tax Credit Calculator for Eligible Employers

SECURE 2.0 · Help me prospect · Calculator or Tool

Elevate your approach with strategic tools and insights

Provisions & priorities

Focus on the SECURE 2.0 provisions that simplify client planning, deliver stronger outcomes, and drive practice growth.

Contributions

Guide clients through new contribution limits and catch-up opportunities that support smarter savings and help grow your advisory revenue.

Distributions

Strengthen your role as a trusted advisor by simplifying distribution rules and helping clients stay compliant.

SECURE act video series

Keep your expertise current with on-demand videos that turn SECURE 2.0 provisions into actionable insights for impactful client conversations.

All SECURE 2.0 Resources

The Proof is in the PEP: Pooled Plan Adoption Examples Advisors Can Use

Growth Strategies ·Expand my practice· Article

The Proof is in the PEP: Pooled Plan Adoption Examples Advisors Can Use

As organizations scale through acquisition, hiring, or expansion, retirement plan administration often becomes more demanding. What once felt routine can quickly require more coordination, more oversight, and more internal time than expected.

For many, the question isn’t whether to provide a retirement plan—it’s whether their current approach can keep pace with the demands of a growing business because as organizations expand, retirement administration often becomes increasingly complex and resource intensive. In these moments, Pooled Employer Plans (PEPs) are emerging more as viable options, offering a more coordinated way to manage complexity, streamline admin, and better position retirement programs for further expansion.

The scenarios below illustrate real-world PEP adoption examples and the moments that prompted employers to consider an alternative. While growth and organizational change are common catalysts, advisors are also seeing employers evaluate PEPs in response to administrative strain, fiduciary concerns, cost pressures, workforce objectives, and limited internal resources. Understanding these broader PEP adoption scenarios can help advisors recognize when a pooled plan conversation may be appropriate.
The Future of Retirement May Be Pooled: The PEP Adoption Trends Advisors Should Know

Growth Strategies ·Expand my practice· Article

The Future of Retirement May Be Pooled: The PEP Adoption Trends Advisors Should Know

Pooled employer plans (PEP) are becoming harder to ignore.

What began as an alternative plan design is now drawing broader consideration, particularly among advisors working with future-focused organizations that face resource constraints. For these employers, PEPs can offer a different approach to plan administration and growth. This pooled employer plan trend also reflects changing expectations around efficiency, governance, and the role advisors play in helping clients evaluate plan structures.

At Ascensus, we’re harnessing the pooled plan momentum and started the PEP Rally to help advisors turn PEP adoption trends into high-energy and effective client conversations. Here, we’ll focus on how pooled employer plans are changing things—and what advisors should do with it. 

The Right Message, In the Right Moment—How AI Personalization is Transforming Participant Engagement

Engage Clients ·Digital Experience & Technology· Article

The Right Message, In the Right Moment—How AI Personalization is Transforming Participant Engagement

In retirement planning, timing is everything—but generic messaging rarely delivers. And while early AI usage in the industry focused on operational efficiency, it’s now shifting from output to outcomes by using participant behavior to power more personalized participant communications that determine what to say, when to say it, and who needs to hear it. The result: a tailored approach where advisors and plan sponsors deliver timely, targeted, and AI assisted messaging that drives more meaningful engagement and better reflects the individuals their plans serve.

READYSAVE®– Help Savers See Retirement Clearly

Engage Clients ·Plan design & capabilities· Article

READYSAVE®– Help Savers See Retirement Clearly

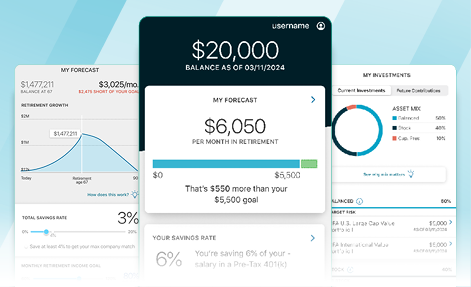
Participants want an easier way to stay connected to their retirement savings—but often lack clear visibility into the tools available to them. This client-ready flyer helps advisors introduce the READYSAVE® participant engagement app and show how savers can monitor progress and take action from their mobile device.

Use this resource to support participant conversations, reinforce plan value, and encourage mobile adoption—without having to explain the technology in detail.

Download the READYSAVE Flyer

6 Reasons Advisors Work with CPAs to Grow Their Practice

Growth Strategies ·Relationship management· Article

6 Reasons Advisors Work with CPAs to Grow Their Practice

For financial advisors, practice growth often comes down to building the right relationships. One of the most valuable can be with a certified public accountant (CPA). Understanding the benefits of a CPA and financial advisor partnership  can help advisors expand their reach, strengthen client relationships, and support more connected financial conversations—without changing the role either professional plays.

Below are six reasons many advisors choose to work with CPAs.

Why Advisors Are Paying Attention to Pooled Plans — and When a PEP Makes Sense

Growth Strategies ·Expand my practice· Article

Why Advisors Are Paying Attention to Pooled Plans — and When a PEP Makes Sense

Pooled Employer Plans (PEPs) are not a new concept in the retirement industry—but they are entering a new phase of relevance.

What began to help employers reduce administrative burden is now a PEP rally. Advisors are increasingly looking at PEPs not just as a solution for clients, but also as a way to rethink how they deliver value, scale their practice, and engage in meaningful conversations.

The shift is subtle, but important. 

Grow Your Practice: CPA and Financial Advisor Partnership Benefits

Growth Strategies ·Expand my practice· Article

Grow Your Practice: CPA and Financial Advisor Partnership Benefits

At some point, every advisor runs into a situation that crosses into tax territory. A business sale. A big liquidity event. A client income picture that keeps changing year to year. You can clearly see the investment strategy. But the tax side is layered and nuanced. That’s where a strong CPA relationship can make a real difference.

You don’t need to be a tax expert. In fact, trying to be a “jack of all trades” can introduce risk and dilute your value. Clients don’t expect you to do everything, but they do expect you to build the right team around them.

A CPA advisory collaboration brings investment strategy and tax planning together in a way that feels more complete, more thoughtful, and more aligned to the client’s full financial picture.

The Most Common Form 5500 Filing Errors Advisors Can Help Sponsors Avoid

Engage Clients ·Digital Experience & Technology· Article

The Most Common Form 5500 Filing Errors Advisors Can Help Sponsors Avoid

Filing Form 5500 accurately is one of the most critical compliance responsibilities plan sponsors face each year. Even small mistakes can trigger scrutiny, lead to costly penalties, or delay processing. The good news is that most Form 5500 filing errors are preventable, with the right preparation, tools, and advisor support.

Starting the Form 5500 process ahead of the deadline gives you and your clients time to catch discrepancies early and address them before they become bigger issues. Keeping thorough, up‑to‑date records—such as participant counts, financial reconciliations, and internal review procedures—strengthen fiduciary oversight and make the process more manageable. It also helps to understand where retirement plan compliance errors most often occur, and the steps that make the filing season smoother and more predictable for your clients.

How AI is Transforming Retirement Plan Administration

Engage Clients ·Digital Experience & Technology· Video

How AI is Transforming Retirement Plan Administration

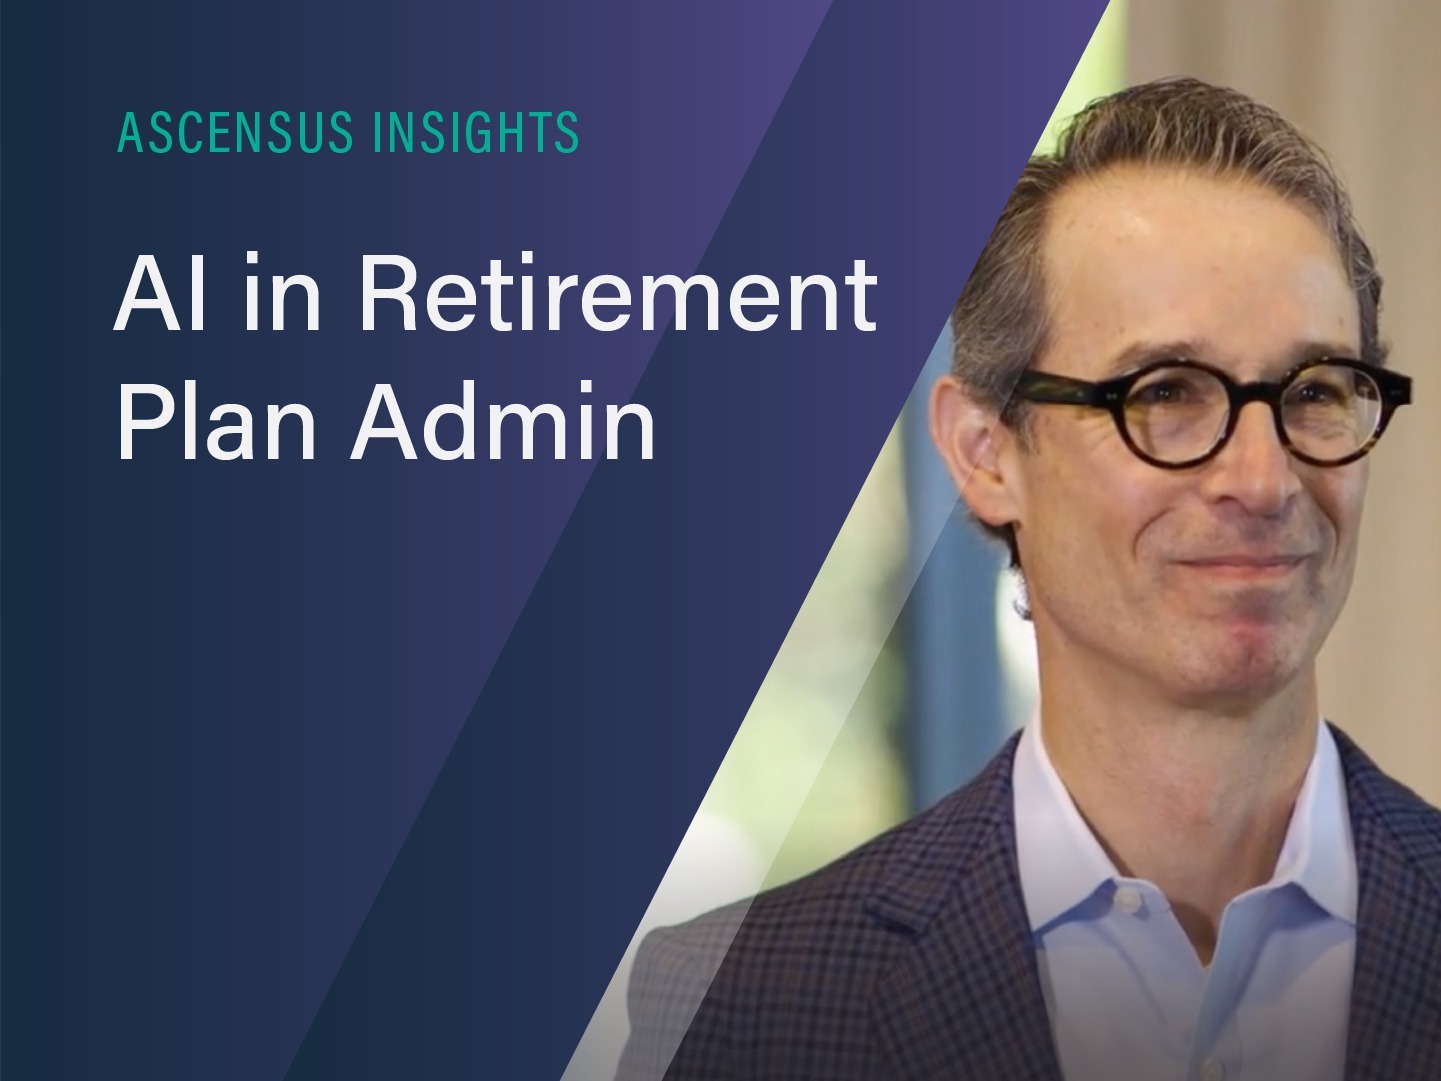
Insights from Ascensus Executive Chairman David Musto

Artificial intelligence is reshaping retirement plan administration by improving data accuracy, streamlining operations, and delivering better outcomes for savers. In this video, Ascensus Executive Chairman David Musto shares how predictive analytics and intelligent automation are changing how retirement plans are designed, managed, and delivered. 

How User Input is Driving Retirement Technology Innovation

Engage Clients ·Digital Experience & Technology· Article

How User Input is Driving Retirement Technology Innovation

Technology developed in a vacuum rarely works in the retirement space.

Real progress happens when the people who use the tools — advisors, sponsors, and participants — shape them. That’s why Ascensus’ development approach and post launch assessment begin not with features, but with your feedback. 

SECURE 2.0 and Retirement Planning: What Advisors Need to Know in 2026

Engage Clients ·Relationship management· Article

SECURE 2.0 and Retirement Planning: What Advisors Need to Know in 2026

Learn more about this year’s SECURE 2.0 changes and how to use them to differentiate your practice and deliver better client outcomes. 

Even as we settle into a new year, the retirement planning landscape continues to shift in response to a changing regulatory and policy environment, market volatility, inflation pressures, and numerous other factors. These changes can bring more complexity—and more opportunities—for advisors and their clients. And while advisors can’t control the markets or changing demographics, they can understand and navigate policy shifts in a way that helps drive the best possible outcomes for their clients.

The first step toward leveraging these policy shifts is understanding what’s changed. Enhanced contribution limits, a Roth-only catch-up requirement, evolving withdrawal strategies, and expanded incentives for small businesses are all redefining how advisors can support clients through this tax season and beyond. 

How Financial Advisors Use Financial Wellness to Grow 401(k) Plans

Growth Strategies ·Expand my practice· Article

How Financial Advisors Use Financial Wellness to Grow 401(k) Plans

In today’s competitive financial advisory market, offering strong investment strategies alone may not be enough to differentiate your practice. Employers are increasingly seeking advisors who offer holistic retirement plan solutions—plans that not only manage assets but also enhance employee engagement and encourage healthier financial habits.

SIMPLE and SEP IRAs for Small Business Clients

Employer education ·Plan design & capabilities· Article

SIMPLE and SEP IRAs for Small Business Clients

SEP and SIMPLE IRAs offers small businesses an easy, affordable way to provide retirement benefits without the administrative complexity of a 401(k). These plans give you straightforward options to support clients who want low-cost setup, predictable responsibilities, and valuable tax advantages.

Balance Forward Individual(k): Flexible Owner-Only 401(k) Plans

Engage Clients ·Plan design & capabilities· Article

Balance Forward Individual(k): Flexible Owner-Only 401(k) Plans

The Balance Forward Individual(k) is a flexible solution for owner-only business clients that want full control over how their retirement assets are invested. With this option, clients manage their account directly through their broker-dealer, while Ascensus provides the plan documents, compliance support, and recordkeeping services.

Ascensus Essentials Individual(k): 401(k) Plans for Owner-Only Business Clients

Engage Clients ·Plan design & capabilities· Article

Ascensus Essentials Individual(k): 401(k) Plans for Owner-Only Business Clients

Ascensus Essentials 3(38) is a streamlined retirement plan solution built for owner-only businesses. It combines automated plan administration with 3(38) fiduciary investment management, helping reduce oversight responsibilities. Advisors can offer clients a professionally monitored plan aligned to small business needs.

Ascensus Essentials Individual(k) featuring American Funds: Streamlined Solutions for Advisors

Engage Clients ·Plan design & capabilities· Article

Ascensus Essentials Individual(k) featuring American Funds: Streamlined Solutions for Advisors

Explore how Ascensus Essentials Individual(k) with American Funds gives you a turnkey retirement solution tailored for owner-only clients. With no asset minimums, transparent pricing, and a professionally managed investment lineup, this plan makes it easy to offer a high-quality 401(k) option while reducing the administrative lift in your practice.

Ascensus Essentials Individual(k) featuring American Funds: Benefits for Small Business Clients

Employer education ·Plan design & capabilities· Article

Ascensus Essentials Individual(k) featuring American Funds: Benefits for Small Business Clients

Use this resource to help small business clients understand the value of Ascensus Essentials Individual(k) with American Funds. With a curated investment lineup, transparent pricing, and streamlined administration, this overview explains how the plan works and why it may be a good fit for owner-only businesses looking for a professionally supported retirement plan.

Ascensus Essentials with Raymond James 3(38): 401(k) Solutions for Advisors

Engage Clients ·Plan design & capabilities· Article

Ascensus Essentials with Raymond James 3(38): 401(k) Solutions for Advisors

The Ascensus Essentials 401(k) managed by Raymond James Direct 3(38) solution helps you strengthen your advisory role by pairing 3(38) investment oversight with streamlined plan administration. With Raymond James managing investment selection and Ascensus providing recordkeeping and compliance support, you can offer clients a 401(k) plan that reinforces your value as a trusted partner to small business clients.

Ascensus Essentials with Raymond James 3(38): Benefits for Small Business Clients

Employer education ·Plan design & capabilities· Article

Ascensus Essentials with Raymond James 3(38): Benefits for Small Business Clients

Use this resource to help clients understand the value of the Ascensus Essentials 401(k) managed by Raymond James Direct 3(38). This turnkey solution simplifies plan management, provides professional 3(38) investment oversight, and offers employees access to a well-supported retirement plan experience.

Daily Value Individual(k): Help Small Business Clients Maximize Retirement Savings

Engage Clients ·Plan design & capabilities· Article

Daily Value Individual(k): Help Small Business Clients Maximize Retirement Savings

Daily Value Individual(k) is a retirement plan option built for owner-only businesses that want daily valuation and broad investment access. With streamlined administration and an open-architecture investment platform, this 401(k) solution supports a flexible approach to managing investments for owner-only clients. 

Support Client and Employee Financial Health with Financial Wellness Essentials

Employer education ·Products and Services· Article

Support Client and Employee Financial Health with Financial Wellness Essentials

Help your clients enhance employee financial well-being with Financial Wellness Essentials. This program offers personalized coaching, education tools, and engagement strategies that support long-term retirement readiness and help employees build financial resilience.

What advisors should know about SEP IRAs, SIMPLE IRAs, and 401(k)s

Engage Clients ·Plan design & capabilities· Article

What advisors should know about SEP IRAs, SIMPLE IRAs, and 401(k)s

Financial advisors often guide small business owners through critical decisions about retirement plans. Understanding the differences between SEP IRAs, SIMPLE IRAs, and 401(k)s can help you recommend the best option based on business size, budget, and growth goals.